The Immigration Services Agency issued the revised permanent residence approval guidelines on 1 October 2026, alongside a new set of guidelines on revoking permanent resident status. The revision settles the question left open when the drafts went to public comment in August: the income and public-burden provisions apply straight away to applications already in the queue, and the rest of the revised text applies to applications filed on or after 1 April 2027.
What the revised guidelines ask for
Three considerations are new.
Household income must have continuously reached a level above the average income of a Japanese household of the same size. The guidelines name no yen figure, and the agency has not published one. The means test as it stood before the revision is on our page covering financial and income requirements.
Pension is assessed forward rather than backward. The applicant's age, enrolment record and projected benefit must reach what someone with 30 years in the employees' pension scheme at that income level would expect to receive.
Japanese-language ability enters for the first time, at B1-equivalent or above on the Common European Framework, broadly JLPT N3 and up. It is set aside for highly skilled professionals and their families, for applicants who completed six years or more of schooling in Japan, and for Japan-born children of permanent residents whose caregiving parent meets B1. Our Japanese language requirements page maps that scale onto the tests.
All three are written as 考慮要素: factors weighed in the decision, not pass-or-fail thresholds.
Household composition is also counted differently. An adult who has left their parents' dependency is assessed on their own income, with the parents' income excluded, removing a cushion the previous wording allowed.
If your application is already pending
Two provisions reach back. The income provision (Part 2, 4(2)) and the provision on not becoming a public burden (Part 2, 5(7)) apply to applications filed on or after 1 April 2026 that were still undecided on 1 October 2026.
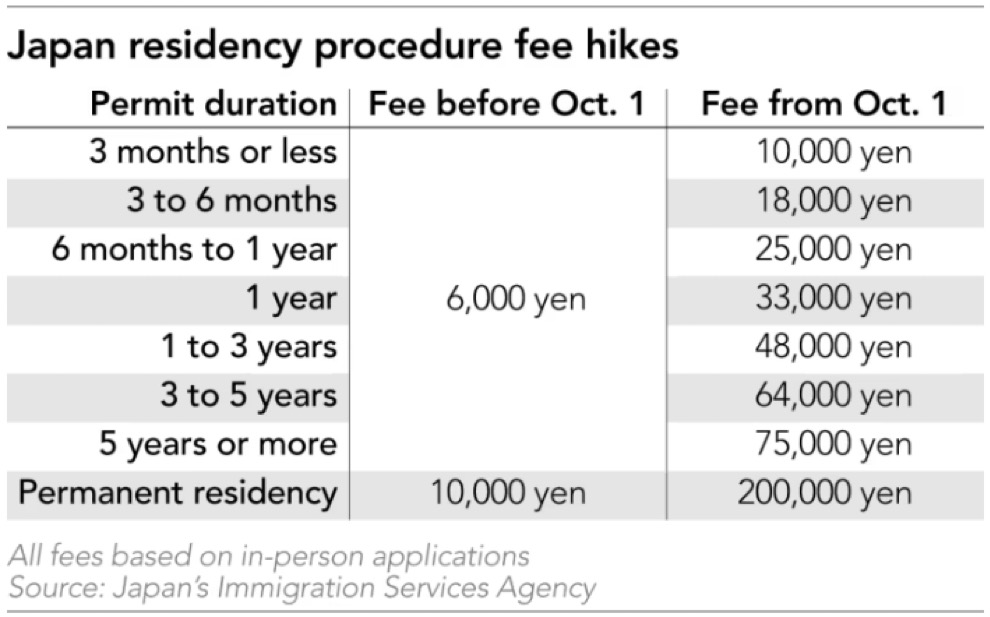
Japanese administrative practice normally judges an application against the rules in force when it was filed; the fee revision of 1 October did exactly that, exempting applications accepted on or before 30 September 2026. Permanent residence has gone the other way. If you filed between 1 April 2026 and 1 October 2026 and no decision has arrived, your household income and your tax and social insurance position are assessed against the new standards, not the ones published when you filed.
There is nothing to refile. What changes is the yardstick, which makes an unprompted supplementary submission worth more than usual: an updated income certificate, or proof an arrear has been cleared.
One transitional concession
For applications filed on or before 31 March 2027, an applicant holding a three-year period of stay is treated as holding the longest available period for the purposes of Part 2, 5(6). Anyone never granted a five-year period keeps that route open until that date.
The revocation guidelines
The 2024 amendment to the Immigration Control Act added paragraphs 8 and 9 to Article 22-4, creating grounds to withdraw permanent resident status. The new guidelines define how they will be used, and operation begins on 1 April 2027.
Paragraph 8 covers failure to observe obligations under the Act, and wilful non-payment of 公租公課: taxes and public charges, including income tax, resident tax, National Health Insurance and National Pension contributions. Wilfulness is read through conduct, meaning repeated demands and collection action without the person making any intention to pay clear. Paragraph 9 covers a sentence of imprisonment for specified offences, including a suspended sentence, with no minimum length attached.
Revocation is not removal from Japan. Except where the Minister of Justice judges continued residence inappropriate, the Minister grants a change to another status on their own authority, in most cases Teijusha (Long-Term Resident).
Neither document addresses special permanent residents, whose status rests on separate legislation.
Nothing here concerns short-stay visitors
Both documents govern a residence status applied for from inside Japan. Visa-exempt entry, short-stay visas and arrival procedure are untouched by either.
What to do before 1 April 2027
If you are planning an application, pull your own records rather than assuming they are clean: a tax payment certificate from your municipality, and your contribution history from Nenkin Net. A gap in National Pension coverage bears on the pension consideration and, separately, on the revocation grounds.
If you already hold permanent residence, the approval guidelines do not reopen your status. The revocation document is the one that applies to you, and the exposure in it is unpaid tax and pension, not income level. An arrear left to accumulate through repeated demands is the pattern described; settling it, or agreeing a payment plan with the issuing office, takes you outside it.
The agency has not said when it will publish the household income figures the income consideration refers to. Check its guideline page, and our own permanent residency reference, before filing on or after 1 April 2027.
Sources: Immigration Services Agency — 永住許可に関するガイドライン(令和8年10月1日改定), Immigration Services Agency — 永住者の在留資格の取消しに関するガイドライン, Immigration Services Agency — revocation guidelines PDF